Funding for higher education opened on 24 March, with deadlines set for 15 May. Eligibility rules vary by residency and immigration status, while repayment conditions—linked to income and inflation—mean graduates may carry debt for up to 40 years after completing their studies.
Pablo Munoz
Applicants can access Tuition Fee Loans —a loan from the government that covers the full cost of the course — and Maintenance Loans, which help meet living expenses during their studies.
These loans allow individuals to undertake their university degree even if they are not able to cover the costs in their present situation, but these will have to be repaid once the borrower of the loan starts earning a stable salary, with an additional interest linked to the Retail Price Index, similar to the rate of inflation, which today is 3.2%. For the student debt accumulated by those applying, which is regulated under Plan 5 of Student Finance England, borrowers will only be required to start paying back the loan in the April after graduation (or they quit university), and only if their yearly gross income is higher than £25,000.
After their earnings cross that threshold, 9% of the student’s monthly salary will be taken out automatically until the debt is repaid, although it will be written off after 40 years, regardless of how much of the debt was repaid. Another important thing to note is that these debts do not affect a person’s credit score, but they might affect important things like affordability when asking for a bank loan.
Annual Tuition Fees differ across the UK: being free in Scotland, £9,790 in England and Wales, and £4,855 in Northern Ireland for UK nationals from each respective country who can demonstrate long-term residence there – most commonly a minimum of three years.
 In Northern Ireland and Scotland, only longstanding residents of these regions will be eligible for loans to cover their respective tuition fees, with students from elsewhere being considered RUK (Rest of United Kingdom), with a set pricing on tuition of £9,790, and this also includes EU nationals.
EU nationals with settled or pre-settled status can also apply for Tuition Fee Loans, although only those with settled status would be eligible for Maintenance Loans, which are dependent on household income and on each student’s situation during their degree – whether they live with their parents, away from home, or in London. EU nationals with pre-settled status are eligible for Maintenance Loans only if they are considered a “Migrant Worker”, which means that they must work around 10 hours a week to be eligible for that extra support.
Regarding Maintenance Loans, which are granted yearly, your pre-tax household income determines eligibility: an income lower than £25,000 means students can receive the maximum loan (ranging from £14,135 if living away from home in London, to £10,830 if living away from home outside London), whereas students from households with an income higher than £58,387 can only receive the minimum loan (ranging from £7,039 if living away from home in London, to £5,048 if living away from home outside London).
This means the amount each student receives depends on their living situation, whether they live with their parents, away from home, away from home in London, or studying a year abroad.
EU nationals without settled or pre-settled status will be treated as international students, who are not eligible for Student Finance and are, furthermore, charged extra for their course, with annual rates ranging from £18,000 for humanities degrees to more than £70,000 for clinical degrees.
According to the Office for National Statistics, through the 2021 Census, Latin American-EU was among the most common dual nationality, which makes a case like this likely: a student from Latin America who holds an EU passport and has settled status, and applies for Tuition Fee Loans and Maintenance Loans at the maximum rate, living away from their London home during their three-year degree, will end university with a £61,860 student debt.
Since this can feel overwhelming, there are other options to consider, like degree apprenticeships, by which big capital companies, like PwC, Goldman Sachs, or Blackrock, pay the fees and employ students while they undertake their chosen degree. These are highly competitive slots.
Another good way to reduce student debt is through scholarships offered by universities, like the UCL Global Undergraduate Scholarship, which offers full coverage of tuition and living costs for overseas fee-payers who can demonstrate a high academic record.
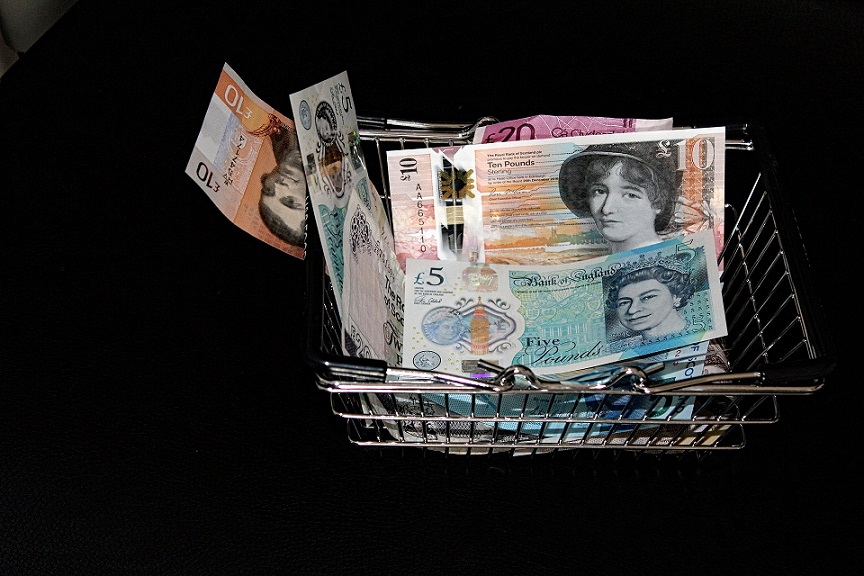 Charitable grants can also lift some of the economic burden imposed by student debts, like the Turn2Us grants—an initiative by small UK charities to give money to students from specific backgrounds. Scholarships and grants can also be found in the UCAS scholarship tool, an online hub with a list of nearly 800 scholarships and bursaries.
To apply for student finance click here.
(Photos: Pixabay)

.jpg)